Repatriating Profits from Nepal: What Foreign Investors Need to Know
The question foreign investors ask when a Nepali subsidiary turns its first profit is rarely about the tax rate. It is about whether the money can actually leave the country, and how long that takes. The tax rate is a known, published number. The repatriation approval is where deals stall, and almost always for the same reason: something was skipped at entry that only becomes visible when someone tries to send money out.
Prepared by Nishant Marasini and team · Position stated as at 22 September 2026
Repatriation in Nepal is not a bank transfer. It is a regulatory approval followed by a bank transfer, and the approval is where the entry-stage paperwork gets checked a second time.
The repatriation approval process
Once a Nepali company declares a dividend, the company (or the investor, depending on how the filing is structured) applies to Nepal Rastra Bank for approval to remit that dividend abroad. NRB checks three things before it approves: that the underlying foreign investment was registered with NRB in the first place, that the dividend was validly declared out of audited, distributable profits under a shareholders' resolution, and that the applicable withholding tax has been deducted and deposited with the Inland Revenue Department before the net amount is cleared for transfer.
The paperwork typically required includes the audited financial statements supporting the profit the dividend is drawn from, the board and shareholders' resolutions declaring the dividend, the tax clearance or withholding tax payment receipt, and the original NRB registration certificate for the investment being repatriated against. A straightforward dividend repatriation, with clean documentation, usually clears NRB in two to four weeks. Anything that requires NRB to go back and verify the original investment registration — because the file is incomplete, or because the registered investor name does not exactly match the shareholder register — takes longer, sometimes considerably longer.
The single most common blocking mistake
The failure that comes up more than any other: an investor whose capital inflow was never properly registered with NRB at entry, or was registered against a different corporate name or a different amount than what was actually transferred, tries to repatriate profits years later and discovers the approval cannot proceed until that original registration gap is resolved. NRB will not approve a dividend repatriation against an investment it does not have on record as validly registered. Fixing this retroactively — reconstructing the paper trail for a capital inflow that happened years earlier, sometimes under different bank relationship managers or before a change in the investor's own corporate name — is far more difficult than registering it correctly would have been at the time. This is the practical reason the entry-stage NRB registration step is not optional paperwork to get to later: it is the record every future repatriation is checked against.
Withholding tax on dividends
Nepal applies withholding tax at source on dividends distributed by a resident company, including dividends paid to foreign shareholders. The standard rate applied to dividend distributions has typically sat at 5 percent, but this is a rate set and periodically revisited through the annual Finance Act, not a fixed constant in FITTA or the Income Tax Act's core structure — it should always be verified against the Finance Act in force for the income year in which the dividend is declared, since Nepal's annual budget has, in past years, adjusted withholding rates on specific categories of income. Whether a lower rate applies under a double taxation avoidance agreement between Nepal and the investor's home jurisdiction depends on the specific treaty and on the investor actually claiming treaty relief with the correct residency certification — it is not applied automatically.
The company distributing the dividend deducts the withholding tax and deposits it with the Inland Revenue Department; the amount that gets NRB clearance for outward remittance is the net figure after that deduction.
The mechanics of converting and wiring out
Once NRB approval for the repatriation is issued, the process becomes a standard banking transaction, but a specific one: the company's Nepali bank converts the approved NPR amount to the foreign currency of the remittance (almost always US dollars, though the investor's home currency is used in some cases) at the prevailing exchange rate on the transaction date, and wires it to the investor's designated foreign bank account, referencing the NRB approval letter. Banks generally will not process an outward remittance of this nature without seeing the NRB approval in hand — it is not something a bank has discretion to waive.
Capital repatriation on exit or divestment
Repatriating the original invested capital, as opposed to profits, arises on a sale of shares, liquidation, or buy-back, and follows a related but separate process. NRB approval is again required, and the amount that can be repatriated is assessed against the originally registered capital, any capital gains realised on disposal, and capital gains tax due on that gain — which for a foreign investor disposing of shares in a Nepali company is a separate assessment from dividend withholding tax and is calculated on the difference between the acquisition cost recorded at entry and the disposal proceeds. This is a second reason the entry-stage NRB registration matters years in advance: the acquisition cost NRB and the tax authority will accept for capital gains purposes is the amount that was actually registered as invested capital, not what a later reconstruction claims it was.
For a share sale to another foreign investor, or a buyback by the company, the transaction itself typically needs DOI's acknowledgment or approval before NRB will process the repatriation of proceeds, since a change in foreign shareholding is, in substance, the same kind of event DOI approved at entry.
Other recurring mistakes
- Declaring a dividend out of unaudited or provisional accounts. NRB and the company's own bank expect the dividend to be traceable to audited financial statements for the relevant year; a dividend declared against management accounts alone tends to get queried.
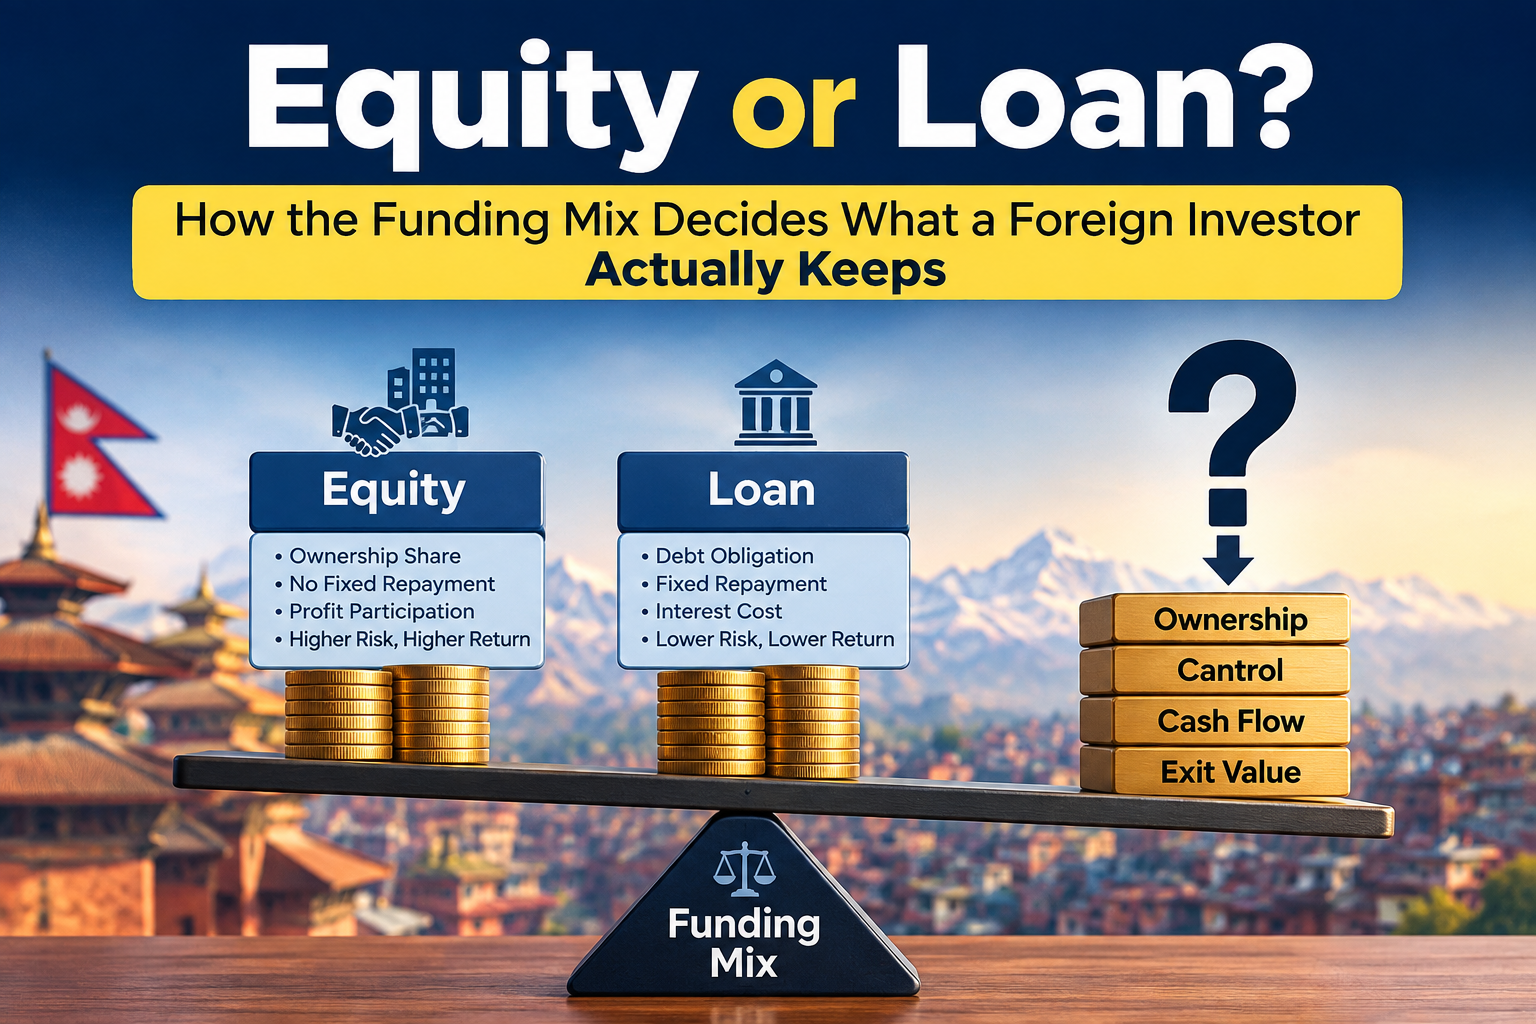
- Treating loan repayments to the foreign parent as dividends, or vice versa. Shareholder loans and equity capital are repatriated through different mechanisms with different NRB documentation, and the two are not interchangeable simply because the ultimate recipient is the same entity.
- Assuming repatriation approval is a formality once the tax has been paid. Paying withholding tax is necessary but not sufficient — NRB's review of the underlying registration and the validity of the dividend declaration happens independently of the tax payment.
What this means in practice
The repatriation process itself, once every underlying document is in order, is not slow by regional standards. What makes it slow, in the cases that actually run into trouble, is almost always a gap that opened up at entry — an investment that was not registered, or was registered incorrectly — surfacing only when someone tries to close the loop years later. Getting the NRB registration right at the point capital first enters Nepal is, in a very direct sense, the same task as getting the repatriation right when profits or capital eventually need to leave.
Authored by CA CA Nishant Marasini
Chartered Accountant, MBS & BA LLB. Advising international investors, corporations, and startups on cross-border transactions, valuation, and regulatory compliance in Nepal.